What is the scope and industry significance of the Artificial Intelligence (AI)-Powered Pathology Analysis System Market?
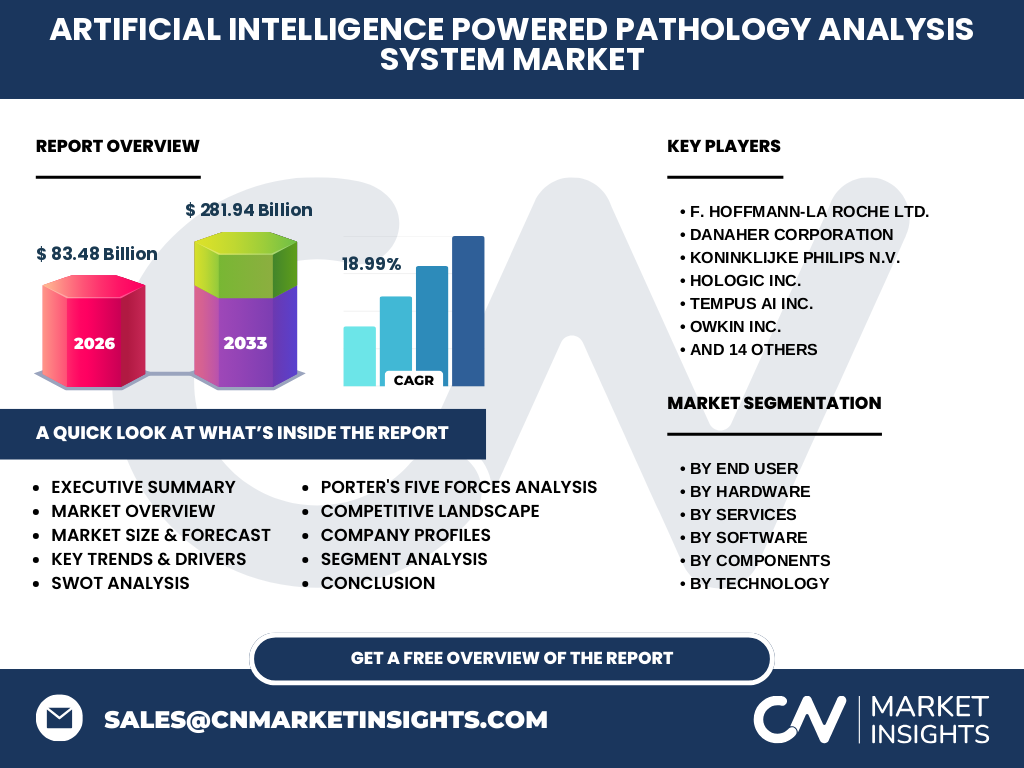
Our analysis indicates that the Artificial Intelligence (AI)-Powered Pathology Analysis System Market encompasses computational diagnostic tools transforming anatomical pathology. Valued at 83.48 Billion in 2026, this sector integrates machine learning algorithms with digital slide scanners to enhance diagnostic accuracy, reduce inter-observer variability, and streamline laboratory workflows for clinical and research applications.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
The market is propelled by a rising global cancer burden and a critical shortage of board-certified pathologists. However, stringent FDA and CE-IVD regulatory clearance pathways act as market restraints. Integration challenges involve legacy laboratory information system interoperability, while significant opportunities lie in predictive biomarker discovery for oncology therapeutics.
Emerging Trends and Growth Patterns in Digital Pathology
The shift toward multi-modal data integration is reshaping the industry, combining computer vision with genomic profiling. Innovators like Tempus AI Inc. and Owkin Inc. are leading this trend by leveraging federated learning, enabling hospitals to train diagnostic models securely without compromising patient data privacy.
How did COVID-19 impact the Artificial Intelligence (AI)-Powered Pathology Analysis System Market?
The pandemic acted as a powerful catalyst for remote digital pathology adoption. Lockdowns forced pathology departments to transition from physical light microscopes to cloud-based viewing platforms. This operational necessity accelerated regulatory approvals and cemented a permanent recovery trajectory focused on decentralized diagnostic workflows.
Competitive Benchmarking and Market Concentration
Industry leadership is contested between established medical device conglomerates and agile software innovators. Major players like F. Hoffmann-La Roche Ltd., Danaher Corporation, and Koninklijke Philips N.V. leverage extensive distribution networks, while specialized startups such as Ibex Medical Analytics Ltd. drive rapid algorithmic differentiation.
Executive Summary of Key Findings
Our comprehensive research establishes that the Artificial Intelligence (AI)-Powered Pathology Analysis System Market is entering an aggressive expansion phase. Driven by surging clinical demand for precision oncology, the market is positioned for exceptional financial and technological acceleration through the end of the decade.
Market Forecast and Long-Term Projections from 2027 to 2033
Based on our econometric modeling, the market is projected to skyrocket from 2027 to 2033, reaching an astounding 281.94 Billion by 2033. This trajectory represents a robust CAGR of 18.99%, fueled by widespread clinical adoption and reimbursement code expansion across North America and Europe.
Granular Segmentation Analysis
The market breaks down across several critical vectors: By End User (Hospitals, Diagnostic Laboratories, Research Institutes, Pharmaceutical And Biotech Companies), By Hardware (Slide Scanners, Digital Microscopes, Servers And Storage Systems, High Performance Computing Systems, Imaging Devices), By Services (Installation And Integration Services, Maintenance And Support Services, Consulting Services, Training And Education Services, Data Analysis And Interpretation Services), By Software (Image Analysis Software, Workflow Management Software, Data Management Software, Reporting And Visualization Software, Quality Control Software), By Components (Software, Hardware, Services), and By Technology (Machine Learning, Computer Vision, Natural Language Processing).
Geographic Distribution and Regional Market Performance
Regional performance varies due to differing healthcare infrastructure investments and regulatory frameworks. North America currently dominates revenue share, supported by early technology adopters and favorable reimbursement policies, whereas Asia-Pacific demonstrates the fastest growth rate driven by expanding hospital modernization initiatives in countries like Japan and South Korea.
In-Depth Regional Review of Adoption Barriers and Catalysts
European markets benefit from unified CE-IVD directives yet face localized procurement hurdles across fragmented national healthcare systems. Conversely, the US market deals with stringent CAP/CLIA validation requirements, favoring vendors with robust clinical trial data and seamless integration capabilities with major electronic health record systems.
Strategic Positioning of Leading Companies
Market participants deploy distinct competitive strategies. Industry heavyweights like Hologic Inc. and Koninklijke Philips N.V. focus on end-to-end hardware-software ecosystems, whereas niche specialists such as Mindpeak GmbH, Aiosyn, and DeepBio Inc. concentrate on hyper-accurate algorithms for specific cancer typologies like prostate and breast pathology.
Porter's Five Forces Analysis of Industry Rivalry
Competitive rivalry is intense, driven by continuous algorithmic advancements from firms like Lunit Inc. and Aiforia Technologies Plc. Supplier power remains moderate due to specialized hardware dependencies, while the threat of substitution is low given the irreplaceable clinical necessity of expert pathological validation.
SWOT Analysis of the AI Pathology Sector
Key Strengths include high diagnostic precision and workflow efficiency. Weaknesses involve high initial capital expenditure for compute infrastructure. Opportunities center on decentralized teleradiology networks, while Threats encompass evolving cyber security regulations and potential algorithmic bias liabilities.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw biopsy tissue procurement and high-resolution glass slide staining reagents, progressing through digital image acquisition via optical scanners by vendors like 3DHISTECH Ltd., and culminating in cloud-based AI inference delivered to clinical end-users via enterprise software platforms.
Investment Insights and High-Potential Areas
Venture capital and strategic acquirers should prioritize software platforms offering multi-modal biomarker quantification and interoperable workflow tools. Companies partnering with cloud giants like Google Cloud are particularly well-positioned to scale processing capabilities for massive petabyte-scale pathology datasets.
Conclusion and Strategic Key Takeaways
The Artificial Intelligence (AI)-Powered Pathology Analysis System Market is transitioning from experimental validation to standard clinical practice. Stakeholders must prioritize interoperability, regulatory compliance, and clinical validation studies to capture market share in this fast-evolving, high-growth healthcare technology landscape.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with chief pathologists, trade registry data from medical device associations, secondary macroeconomic healthcare spending indicators, and proprietary vendor revenue disclosures to ensure absolute market intelligence accuracy.
Scope of the Report and Coverage Parameters
This report covers global market sizing, regional revenue splits, technology segmentations, and competitive profiling from 2026 through 2033. Excluded from this scope are traditional manual microscopy consumables and non-diagnostic veterinary pathology applications, focusing strictly on human clinical and research markets.
Recent Industry Developments and Strategic Moves
Recent market dynamism is highlighted by strategic partnerships and product clearances. Firms such as OptraSCAN Inc., Proscia Inc., Tribun Health, Visiopharm A/S, Indica Labs Inc., and AIRA Matrix Pvt. Ltd. have actively announced commercial expansions, regulatory milestones, and collaborative distribution agreements to enhance their global footprint.